Tag Archives: acupuncturist insurance

Acupuncturist reviewing professional liability, general liability, and property insurance options

Which Acupuncture Insurance Policy Type Is Right for Your Practice?

Which Acupuncture Insurance Policy Type Is Right for Your Practice?

Choosing an acupuncture insurance policy type takes more than comparing premiums. Your policy should match how you practice, where you practice, the services you provide, the property you own, and what happens if someone reports a claim after a policy period ends.

For acupuncture professionals, two questions matter most: What coverage does your practice need, and does your professional liability policy use a claims-made or occurrence form? AAC also offers Preferred and Elite program options, plus endorsements for additional insureds, premises and general liability, and business personal property.

Transcript access: We could not independently locate a transcript or download link for the supplied video in the current indexed AAC materials. If the legacy page contains a transcript asset, preserve that existing asset and link during the WordPress migration.

Start with professional liability coverage

Professional liability, often called malpractice insurance, addresses allegations that arise from professional services. The National Association of Insurance Commissioners describes medical professional liability insurance as protection for licensed health professionals against liability associated with wrongful practices, including bodily injury, medical expenses, property damage, and defense costs.

For an acupuncturist, start by checking whether the policy covers the services you actually provide. AAC says its acupuncture policy generally covers services within the practitioner’s state-defined scope of practice, subject to policy exclusions. The actual policy and endorsements therefore matter more than a marketing summary.

If your practice includes herbal medicine, cosmetic or facial acupuncture, or other modalities, confirm how the policy treats each service. Also confirm that the service falls within your state’s scope of practice.

Claims-made vs. occurrence: the timing matters

The policy form determines when coverage can respond.

An occurrence policy generally responds when the covered incident occurs during the policy period, even if someone makes the claim later. A claims-made policy generally responds when someone makes the claim while the policy remains active, subject to the policy terms, including any retroactive date and reporting or extended-reporting provisions.

Consider a simple example. You provide care in 2026, but a patient makes a claim in 2028.

With occurrence coverage, the policy in force when the 2026 event occurred generally responds, assuming the policy covers the event. With claims-made coverage, the policy in force when the patient makes the claim generally responds, and the underlying event must fall within the policy’s applicable retroactive coverage.

This distinction matters when you change carriers, stop practicing, retire, or allow a claims-made policy to lapse. The National Association of Insurance Commissioners and the American Medical Association explain that extended reporting, often called “tail” coverage, can help address claims that arrive after a claims-made policy ends.

AAC’s current FAQ states that its claims-made option converts to occurrence coverage without charge after ten years. AAC also states that practitioners moving from another claims-made policy may qualify for retroactive coverage, subject to underwriting. Because policy terms can change, verify the current policy wording and transition provisions before you rely on those features.

What other coverage might your practice need?

Professional liability does not address every business risk.

Premises and general liability

Premises liability can address certain non-malpractice injuries or property-damage allegations that occur in the treatment area. For example, a patient could slip on a wet floor or trip over a hazard.

AAC explains that its general liability coverage can extend beyond the immediate treatment area. Depending on the policy terms, it can address risks such as injuries to invited guests, certain personal-injury claims, medical expenses, products liability, and fire or water legal liability.

If you lease space, share a clinic, or regularly welcome patients and other visitors, ask whether your premises or general liability coverage matches your contractual and operational responsibilities.

Business personal property

Business personal property coverage can address certain losses involving business equipment and furnishings that do not form permanent parts of the building. AAC currently describes coverage for items such as treatment tables and furniture, with a $10,000 limit and $500 deductible. Practitioners can request higher limits.

Ask one practical question: If a covered event damages or destroys the equipment you need to operate, what coverage responds?

Additional insureds and practice entities

Landlords, hospitals, clinics, or other organizations may ask you to add them as additional insureds. AAC explains that practitioners can request additional-insured coverage by endorsement and that the policy can treat limits differently depending on the circumstances.

Your professional corporation or other business entity presents a separate issue. Review the policy structure with AAC or your insurance professional so the named insureds and entities match your actual practice structure.

Preferred, Elite, and risk-management options

AAC currently describes Preferred as its standard program. Under the current program description, Elite provides a 30% discount when practitioners agree to use an arbitration form and informed-consent form with patients. The council also says its policy does not universally require arbitration and informed consent, although state requirements and clinical circumstances can vary.

Do not use a discount as a substitute for understanding the forms. Review each document, make sure it fits your practice, and confirm applicable state requirements.

A practical policy-review checklist

Before you buy or renew acupuncture professional liability insurance, ask:

  1. What professional services and modalities does the policy cover?
  2. What exclusions or endorsements apply to my practice?
  3. Does the professional liability policy use a claims-made or occurrence form?
  4. If it uses claims-made coverage, what is the retroactive date and what happens when the policy ends?
  5. What reporting obligations apply if I learn about an incident or complaint?
  6. Do I need premises or general liability in addition to professional liability?
  7. Do I need business personal property coverage?
  8. Does my landlord, clinic, employer, or another organization require additional-insured status?
  9. Does the policy correctly reflect my practice entity and ownership structure?
  10. What liability limits, deductibles, program conditions, and current premiums apply?

Your answer will depend on the actual policy, your practice structure, the services you provide, and applicable state requirements—not simply on the name of the coverage.

The bottom line

Choosing an acupuncture insurance policy type starts with understanding the risks you want to transfer. Professional liability addresses allegations involving professional services. Premises or general liability can address certain non-malpractice risks associated with the business and premises. Business personal property can address covered losses involving equipment and furnishings. Claims-made and occurrence answer a different question: When does the professional liability policy respond?

If you are reviewing your coverage, read the declarations, endorsements, exclusions, and applicable policy wording—not just the quote. Then ask the insurer to explain any provision that affects your services, practice entity, transition between carriers, or retirement plans.

Talk with AAC about your coverage options

The American Acupuncture Council provides acupuncture-focused professional liability information, coverage options, risk-management resources, and quote assistance. If you are comparing policies or reviewing an existing policy, AAC can help you identify available options and explain the program terms.

Educational disclaimer: This article provides educational information only. It does not provide legal, insurance, financial, or clinical advice. The actual policy, endorsements, exclusions, conditions, and applicable law govern insurance coverage. State requirements and available coverage can vary.

AAC resources

References

  1. National Association of Insurance Commissioners. Medical Malpractice Insurance. Updated April 1, 2026. NAIC
  2. American Acupuncture Council. Frequently Asked Questions. AAC FAQ
  3. American Acupuncture Council. Coverage Options. AAC Coverage Options
  4. American Acupuncture Council. AAC Policy. AAC Policy
  5. American Medical Association. Hospital & residency program closure implications FAQs. AMA
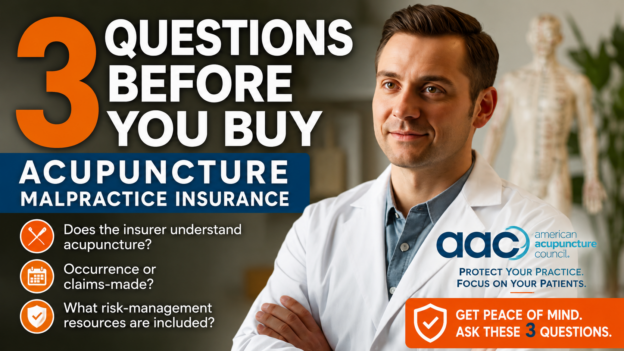
Acupuncturist reviewing three questions before buying acupuncture malpractice insurance

3 Questions to Ask Before Buying Acupuncture Malpractice Insurance

3 Questions to Ask Before Buying Acupuncture Malpractice Insurance

Choosing malpractice coverage is about more than finding a low premium. Before buying acupuncture malpractice insurance, ask three practical questions: Does the insurer understand acupuncture, how does the policy respond to claims over time, and what risk-management resources are included? These answers can affect how well the policy fits your practice.

Introduction

Choosing professional liability insurance is a practice-management decision, not simply a price comparison. For acupuncturists, the policy should fit the services you provide, the way your practice is structured, and your plans for changing carriers or eventually retiring. The American Acupuncture Council’s original post highlights three useful questions to ask before purchasing coverage: whether the program has acupuncture-specific experience, whether the policy is occurrence or claims-made, and what risk-management options are available.

Why acupuncture-specific insurance experience matters

A general healthcare policy is not automatically equivalent to coverage designed around acupuncture. Before buying a policy, ask the insurer to explain how it treats the services and modalities you actually provide and whether there are exclusions or underwriting requirements that could affect them.

AAC states that its professional liability program is designed for acupuncture and that coverage can vary according to the practitioner’s scope of practice and the services involved. Its current policy information also describes additional coverage options and a range of liability limits. Those details are reasons to read the actual policy and endorsements rather than relying on a summary or sales quote alone.

Question 1: Does the insurer have experience with acupuncture?

Ask whether the insurer and claims team routinely handle acupuncture professional liability matters. Then ask a more useful follow-up: “What exactly is covered for the services I perform?”

That question is especially important if your practice includes services beyond straightforward needling, such as herbal medicine, cupping, moxibustion, cosmetic or facial acupuncture, injection therapy, or another modality. Coverage depends on the policy language, underwriting, applicable exclusions, and the law and scope of practice where you work.

Question 2: Is the policy occurrence or claims-made?

This is one of the most important technical questions because the policy form determines when coverage can respond. The National Association of Insurance Commissioners explains that claims-made coverage generally responds when a claim is reported while the policy is in force, subject to the policy’s terms and any extended reporting period. Occurrence coverage generally responds based on when the covered event occurred, even if the claim is made after the policy has ended.

With a claims-made policy, ask what happens if you change carriers, stop practicing, or retire. You may need an extended reporting period, commonly called tail coverage, or prior-acts coverage from a new carrier. The exact solution depends on the policy and transition.

AAC’s current FAQ states that its claims-made option converts to occurrence coverage without charge after ten years and that retroactive coverage may be available for practitioners moving from another claims-made policy, subject to underwriting. Because insurance terms can change, practitioners should confirm the current policy wording and transition provisions before relying on those features.

Question 3: What risk-management options are included?

Insurance is only one part of risk management. Ask what resources the insurer provides to help reduce disputes and respond when a complaint develops.

AAC currently offers Preferred and Elite program options. Its FAQ states that the Elite program provides a premium discount when practitioners use approved arbitration and informed-consent forms as part of their intake process. AAC also describes claims and risk-management support for members.

Informed consent should not be treated as a substitute for sound clinical judgment, appropriate documentation, communication, referral, or compliance with state requirements. Likewise, an arbitration agreement may have legal and jurisdiction-specific requirements. Practitioners should use only forms approved for their program and practice and should obtain independent legal advice when appropriate.

What to compare before you buy

Before selecting a policy, compare more than the annual premium. At minimum, review the policy form; per-claim and aggregate limits; covered services and exclusions; defense provisions; prior-acts or retroactive coverage; tail or extended reporting provisions; additional insured and business-entity coverage where applicable; and risk-management resources.

Also ask how a claim or incident should be reported. A policy may impose notice requirements, and failing to follow them can create coverage issues. Keep the policy, endorsements, declarations, and approved forms together with your practice’s insurance records so that your staff can locate them quickly if a problem arises.

Benefits, limitations, and safety considerations

The main benefit of asking these questions is clarity. A policy that looks inexpensive may have a different policy form, exclusions, limits, or transition requirements than another policy. On the other hand, a higher premium does not automatically mean better coverage. The right comparison is between the actual protections and obligations in each policy.

Professional liability insurance also does not replace clinical risk management. Accurate patient histories, examination findings, treatment plans, informed consent, appropriate referrals, and detailed records remain important parts of safe practice. AAC’s guidance on patient records emphasizes documenting the reason for the visit, medications and allergies, clinical findings, diagnosis, treatment plan, and care provided.

Insurance requirements, scope-of-practice rules, arbitration law, and documentation requirements vary by jurisdiction. Practitioners should verify current requirements with the applicable licensing board, insurer, attorney, or other qualified professional.

A practical three-question checklist

Before you buy or renew, ask:

1. Does this insurer have meaningful experience with acupuncture and my specific services?

2. Is the policy occurrence or claims-made, and what happens to coverage for my past work if I change carriers, stop practicing, or retire?

3. What risk-management resources, forms, claims support, and program options are included—and what conditions apply?

Conclusion

The goal is not simply to buy malpractice insurance. It is to understand what you are buying before you need it. For acupuncturists, three questions provide a practical starting point: acupuncture-specific experience, policy form and long-term coverage, and risk-management support.

If you are comparing coverage, review the actual policy documents and ask the insurer to explain anything you do not understand. AAC provides acupuncture-focused professional liability information, coverage options, claims and risk-management resources, and a Quick Quote for practitioners who want to compare their options.

Educational disclaimer

This article is for educational purposes only and does not provide legal, insurance, financial, or clinical advice. Insurance coverage is governed by the actual policy, endorsements, exclusions, and applicable law. State licensing and insurance requirements vary. Consult your insurance professional, attorney, licensing board, or other qualified adviser regarding your specific circumstances.

Related American Acupuncture Council Resources

References

  1. American Acupuncture Council — original article
  2. AAC — Frequently Asked Questions
  3. AAC — AAC Policy
  4. AAC — Coverage Options
  5. AAC — Claims Service & Risk Management
  6. AAC — Importance of Keeping Detailed Patient Records
  7. AAC — The Importance of Patient-Informed Consent
  8. AAC — Acupuncture Malpractice Quick Quote
  9. National Association of Insurance Commissioners — Medical Malpractice Insurance
  10. AMA Insurance — Claims-Made vs. Occurrence Medical Malpractice Insurance
  11. TMLT — Claims-Made vs. Occurrence

Talk With AAC About Your Coverage Options

If you are comparing acupuncture malpractice insurance, AAC can help you review available coverage options and request a Quick Quote. Visit AAC’s Acupuncture Malpractice Quick Quote to begin.

This article is for educational purposes only and does not provide legal, insurance, financial, or clinical advice. Insurance coverage is governed by the actual policy, endorsements, exclusions, and applicable law. State requirements vary.

acupuncturist insurance policy, acupuncturist insurance

Why Acupuncturist Insurance Is Essential for Your Practice

Running an acupuncture practice is about more than helping patients find relief — it’s also about protecting your business, reputation, and financial future. With the growing popularity of acupuncture and the hands‑on nature of your work, having the right insurance coverage isn’t just smart — it’s essential. That’s where acupuncturist insurance comes in, offering peace of mind and tailored protection for professionals like you.

Understanding the Risks Your Practice Faces

As an acupuncturist, you encounter unique risks that many other small businesses don’t face. Even with careful training and thoughtful patient communication, the reality is that unexpected situations can happen — and when they do, the financial impact can be substantial. Acupuncturist insurance helps protect your practice from these uncertainties, and this helps you stay focused on delivering quality care.

Here are some common challenges acupuncture business owners may face:

  • Patient claims or dissatisfaction that lead to costly legal defense
  • Property loss or damage to your clinic space or equipment
  • Employee injuries on the job, requiring medical care and wage coverage
  • Business interruption occurs when unforeseen issues temporarily halt operations

What Acupuncturist Insurance Covers

Insurance for acupuncturists goes beyond just basic liability protection. A reputable provider such as the American Acupuncture Council offers a range of insurance options specifically designed to safeguard your practice. Some key coverages to consider include:

  • Professional Liability Insurance – Protects against claims of negligence, improper treatment, or injury during patient care.
  • Business Owner’s Policy (BOP) – Combines property and general liability coverage to protect your clinic building, contents, and third‑party injuries.
  • Workers’ Compensation Insurance – Covers medical expenses and partial wage replacement if an employee obtains an injury at work.
  • Additional Protections – May include cyber liability, equipment coverage, and business property protection — further enhancing your financial security.

With the right insurance coverage in place, you can mitigate financial risks and operate with confidence, knowing that your practice has insurance tailored to the needs of acupuncture professionals.

How Insurance Helps Your Practice Thrive

Securing acupuncturist insurance isn’t just about preparing for the worst — it also brings long‑term benefits that contribute to your practice’s success. For example:

  • Peace of Mind — Knowing you’re covered if unexpected challenges arise.
  • Professional Credibility — Demonstrates to patients that you take responsibility and safety seriously.
  • Compliance Support — Helps you meet legal, regulatory, and lease requirements that may require proof of coverage.
  • Business Continuity Assistance — Provides support in the event of a disruption to your operations.

A well‑designed insurance plan lets you focus on what matters most — helping your patients — while minimizing worry about what could go wrong.

Protect Your Practice Today

Whether you’re just starting your acupuncture journey or you’ve been treating patients for years, acupuncturist insurance is a vital investment in the health of your business. Don’t wait until risks turn into problems — build a solid foundation that supports both your professional reputation and your practice’s future.

—

Call (800) 838‑0383 to get a quote or learn more about customized insurance plans from the American Acupuncture Council — let experienced professionals help you protect your practice with confidence.

insurance for acupuncturists by American Acupuncture Council

Essential Guide to Insurance for Acupuncturists


Like any other alternative treatment, acupuncture comes with risks, including patient complaints that could escalate into legal disputes. Such a scenario can be damaging not only to a professional reputation but also to your finances. However, purchasing insurance for acupuncturists provides essential protection, safeguards your business, and ensures peace of mind.

Today, many insurance providers offer customized policies that allow acupuncturists to choose the coverage that best suits their practice. Coverage options include:

  • Professional liability insurance – protects the professional reputation of acupuncturists. Acupuncture is still vulnerable to damaging complaints despite making advancements in the alternative treatment industry. Thus, taking preventative action to protect your license and practice is necessary.
  • Business personal property (BPP) – covers the named insured for lost, stolen, or damaged business property, such as equipment. For example, you can cover a treatment table, furniture, or other business property that is not a permanent fixture of the building structure by this insurance policy.
  • Premises liability – commonly called slip or trip and fall insurance. It covers the potential risks of a guest on the premises alleging damage to their personal property or injury in the clinic area, such as slipping from a wet spot on the floor, tripping on a frayed rug, or fainting and falling off the treatment table.

Insurance for Acupuncturists by American Acupuncture CouncilHere at the American Acupuncture Council, we have “Additional Insured” coverage to protect an entity, such as a landlord, corporation, or another person, that requests inclusion in your policy. The purpose of this coverage is to protect the AI entity named in a claim that was a result of your actions (or inactions), the AI entity will be defended by your policy. Your policy will cover any damages awarded against the AI, as specified in the liability limit provision.

Running an acupuncture practice comes with its own set of challenges, including potential patient claims that can result in financial stress and legal complications. With the right acupuncture insurance policy, you can focus on delivering high-quality care, knowing your business is protected.

Choosing a reliable malpractice insurance provider is one of the crucial decisions for acupuncturists today. A trusted provider ensures that you never have to worry about unexpected legal or financial risks, allowing you to focus on what matters most—the growth of your business and the welfare of your patients.

—

Are you looking for reliable insurance for acupuncturists? Look no further than the American Acupuncture Council. Call us today at (800) 838-0383.

acupuncture malpractice liability insurance, acupuncture malpractice insurance, acupuncturist business insurance company

Acupuncturist Insurance Offers Must-Have Protection for Your Practice


Like any other business in the health and wellness industry, your acupuncture business should get insurance that protects your finances and professional reputation. For one, acupuncture carries higher risks in terms of malpractice claims. For another, insurance is one of the requirements by the state before giving a license to operate. Therefore, finding a reputable acupuncturist insurance provider is no longer an option but a necessity.

Here are some of the benefits of getting an insurance for an acupuncture business:

Malpractice coverage. Over time, the number of clients that come to your clinic grows. The more clients you have, the higher the chances that a client or two you treat will lodge a malpractice complaint. But you do not need to wait for that to happen before you protect your business and professional reputation. With malpractice coverage from an acupuncture insurance provider, you can rest assured that insurance can cover the financial burden of addressing that complaint.

Premises liability. It is commonly called slip or ‘trip and fall’ insurance. As an insured acupuncturist, you can expect that your policy covers the potential risks of a guest on the premises alleging damage to their personal property or injury in the clinic area, such as slipping from a wet spot on the floor, tripping on a frayed rug or fainting and falling off the treatment table.

Business personal property coverage. An acupuncturist insurance provider can also offer protection to the insured for lost, stolen, or damaged property of the business, such as equipment. For example, the policy can protect items such as a treatment table, furniture, or other business property that is not a permanent fixture of the building structure.

Peace of mind. When you know that something provides protection should somebody file a complaint about your acupuncture business, you can sleep well at night knowing that things are in place by giving you financial coverage to take care of untoward events in relation to your practice.

Are you looking for a reputable acupuncturist insurance provider? Look no further than the American Acupuncture Council. Call us at (800) 838-0383 for inquiries.

Why An Acupuncturist Insurance Is Vital (And How To Find The Best Provider)


You should perform a comprehensive search for prospective providers for products as valuable as acupuncturist insurance. You have to make sure that the company you choose can deliver its promise. Your choice will have a crucial impact on your finances and your professional reputation as an acupuncturist.

Many companies in the market present themselves as the best acupuncturist insurance provider you can find around. However, as the saying goes, “there’s more than meets the eye.” That implies you have to be careful in choosing an acupuncturist insurance product to buy; make sure you do it based on an informed decision – not just on how these companies portray themselves. With that said, here are some crucial things you need to consider when choosing an acupuncturist insurance provider:

  • Experience (you would want to look for an acupuncturist insurance provider with proven track records, probably with decades of industry experience)
  • Good reviews from previous and current clients (there is no better way to learn about how good (or bad) a company is than those who have experienced their product themselves.)
  • Package quotations are transparent (what you see is what you get; what you get is what you pay)
  • The total value of insurance claims they pay out each year (this provides insights into the company’s capability to deliver the insurance protection as promised)
  • Has physical location or office (that means they are legitimate and have the approval from regulating bodies to offer insurance for acupuncturists.)

Some benefits of acupuncturist insurance

  • Offers liability insurance to protect your business and professional reputation from potential malpractice lawsuits;
  • Offers workers’ compensation, covering all employees (except those from independent contractors);
  • Offers premises liability protection or commonly called slip or trip and fall insurance (covers the potential risks of a guest on the premises alleging damage to their personal property or injury in the clinic area such as slipping from a wet spot on the floor, tripping on a frayed rug or fainting and falling off the treatment table)
  • Offers protection for business personal property (can cover the named insured for lost, stolen, or damaged property of the business, such as equipment)

Online looking for a reputable and most qualified acupuncturist insurance provider? Reach out to the team at the American Acupuncture Council today.

Please call (800) 838-0383 for inquiries.