Disclaimer: The following is an actual transcript. We do our best to make sure the transcript is as accurate as possible, however, it may contain spelling or grammatical errors.Due to the unique language of acupuncture, there will be errors, so we suggest you watch the video while reading the transcript.
Click here for the best Acupuncture Malpractice Insurance
Yes. Acupuncture can cause a small amount of bleeding or localized bruising when a needle is inserted or withdrawn. These reactions are recognized in clinical safety research and are usually minor. They are not, however, automatically harmless in every patient: medication use, a bleeding or coagulation disorder, relevant medical conditions, the anatomical site, and the needling technique all influence risk.
For acupuncturists, the practical question is not simply whether a spot of blood is normal. It is whether the patient has been appropriately assessed, the needling approach is suitable, bleeding is controlled, and any unexpected event is documented and managed.
Why can acupuncture cause bleeding or bruising?
Acupuncture needles pass through the skin and may encounter small superficial blood vessels. A small amount of blood at the insertion or withdrawal site can therefore occur. Blood that escapes into nearby tissue may produce a localized bruise or, less commonly, a more noticeable hematoma.
The likelihood of a visible reaction can vary with the location and vascularity of the area, individual tissue characteristics, needle selection, insertion depth and angle, and the degree of manipulation. A small spot of blood does not by itself establish that a treatment was performed improperly. Conversely, persistent bleeding, an expanding hematoma, unusual pain, or symptoms suggesting a deeper injury should not be dismissed as an ordinary treatment response.
How common are bleeding and other acupuncture adverse events?
A 2021 systematic review and meta-analysis of prospective clinical studies found that bleeding was among the more frequently reported minor adverse events. Its pooled estimate was approximately 4.92% of treatments, with a very wide confidence interval (1.18%–11.01%) and substantial between-study heterogeneity. The authors emphasized that studies used differing definitions and methods for recording adverse events; some recorded minor bleeding or local pain that may be considered an expected needling reaction.
The same review estimated serious adverse events at approximately 7.98 per one million treatments. These figures provide context, not a guarantee of safety for an individual patient or a prediction for a particular practice. Different patient populations, practitioner settings, reporting methods, and definitions affect the estimates.
Who may have a higher risk of bleeding or bruising?
Patients taking anticoagulant medication
Anticoagulants reduce blood clotting and can increase the likelihood or duration of bleeding. Examples include warfarin, heparin, and direct oral anticoagulants such as apixaban and rivaroxaban. Medication history should include the drug, dose when known, indication, relevant monitoring information when applicable, and any history of unusual bleeding or bruising.
A large Taiwanese database case-control study published in 2023 examined 13,447,563 acupuncture sessions among 821,946 people. Anticoagulant use was associated with a higher risk of minor bleeding. The study did not find a statistically significant increase in major bleeding for anticoagulant use overall, although certain anticoagulant subgroups had higher observed risks. The findings support careful assessment; they do not establish that acupuncture is universally safe or universally contraindicated for everyone taking these medicines.
Do not advise a patient to stop or change a prescribed anticoagulant or antiplatelet medication to facilitate acupuncture. Any medication decision belongs with the prescribing clinician. When risk is unclear, coordinate with the patient’s medical team and consider whether treatment should be deferred or modified.
Patients with coagulation disorders or relevant medical conditions
Known bleeding disorders, thrombocytopenia, liver disease, a history of unexplained or prolonged bleeding, and other conditions affecting hemostasis warrant additional assessment. The World Health Organization’s 2020 Benchmarks for the Practice of Acupuncture identifies a disturbance of blood coagulation as a contraindication in its benchmark guidance. Practitioners should apply this guidance alongside current clinical information, local regulations, scope of practice, and appropriate medical consultation rather than assuming that every medication-related bleeding risk is identical to a diagnosed coagulation disorder.
Other patient and site considerations
Older or medically complex patients may have multiple factors that influence bruising risk. Needling near visible or palpable superficial vessels, or in areas with greater vascularity, calls for careful anatomical assessment. Ask about prescription medicines, over-the-counter products, supplements, prior bruising, and recent changes in health rather than relying on a brief question about “blood thinners.”
How can acupuncturists reduce preventable bleeding?
Risk reduction begins before the first needle is inserted:
Take and update a relevant history. Ask about bleeding disorders, liver disease, anticoagulants, antiplatelet agents, supplements, prior complications, and unusual bruising or bleeding.
Assess the site anatomically. Identify visible or palpable vessels and structures at risk. Select points, depth, angle, and needle specifications with the patient’s condition and anatomy in mind.
Use appropriate technique. Avoid unnecessary force or aggressive manipulation, and adapt treatment to the patient’s response and clinical circumstances.
Follow infection-control and needle-handling standards. Use sterile, single-use needles and comply with applicable hygiene and sharps-disposal requirements.
Explain material risks and obtain informed consent. Discuss the possibility of minor bleeding or bruising and any patient-specific precautions in understandable language.
Observe and reassess. Inspect needled sites when appropriate, particularly when the patient’s history or treatment location raises concern.
WHO guidance recommends attention when withdrawing needles from body regions prone to bleeding and pressing with a clean swab when needed. It also emphasizes appropriate needle depth, technique, informed consent, and complete treatment records.
What should you do if a patient bleeds after acupuncture?
For slight, localized bleeding, withdraw the needle carefully and apply direct pressure with a clean, dry sterile swab until bleeding stops. Do not rub the site. Reassess the area before the patient leaves. If a bruise or hematoma develops, assess its size, progression, pain, and associated symptoms; follow appropriate clinical protocols and seek medical evaluation when warranted.
Persistent bleeding, rapidly expanding swelling, severe or escalating pain, marked weakness or dizziness, or signs of a significant vascular injury require prompt assessment and escalation. Suspected deep injury or systemic symptoms should not be managed as routine superficial spotting. Follow emergency procedures and arrange urgent medical care when indicated.
Document the patient’s relevant history, the site and technique, the event and its timing, observations, actions taken, the patient’s response, advice or referral, and follow-up. Documentation should be factual and completed in accordance with applicable professional and legal requirements.
Is bruising after acupuncture dangerous?
A small, localized bruise that does not enlarge and resolves without other symptoms is generally a minor reaction. A large or expanding hematoma, persistent bleeding, severe pain, numbness, weakness, or symptoms that suggest a deeper injury require further assessment. Patients should be told how to contact the practitioner and what changes warrant medical attention.
Practitioners should avoid promising that bruising will never occur. Clear pre-treatment communication helps patients distinguish an anticipated minor reaction from a symptom that needs follow-up.
What this means for acupuncture practice
Bleeding and bruising are recognized possible effects of acupuncture, but prevention and response depend on sound clinical judgment. A careful medical and medication history, anatomical knowledge, appropriate needling, informed consent, direct pressure when indicated, and accurate documentation are practical foundations of patient safety.
The American Acupuncture Council (AAC) supports acupuncturists through professional liability coverage and risk-management resources. Practitioners can learn more about AAC claims service and risk management and review AAC policy information to understand available coverage and services. Coverage terms vary; consult the applicable policy and insurer for specific questions.
References
World Health Organization. WHO Benchmarks for the Practice of Acupuncture. Geneva: WHO; 2020. ISBN 978-92-4-001688-0. WHO publication.
Acupuncture-related adverse events: systematic review and meta-analyses of prospective clinical studies. BMJ Open. 2021;11:e045961. doi:10.1136/bmjopen-2020-045961.
Hsieh HT, Chou HJ, Wu PY, Lin SK. Bleeding risk after acupuncture in patients taking anticoagulant drugs: A case control study based on real-world data. Complement Ther Med. 2023;74:102951. doi:10.1016/j.ctim.2023.102951. PMID: 37141924.
Educational disclaimer: This article is for educational purposes and is not a substitute for individualized medical advice, diagnosis, treatment, or consultation with a qualified healthcare professional. Acupuncturists should follow applicable laws, professional standards, scope-of-practice requirements, current clinical guidance, and emergency protocols. Patients should not stop or change prescribed medication without guidance from the prescribing clinician.
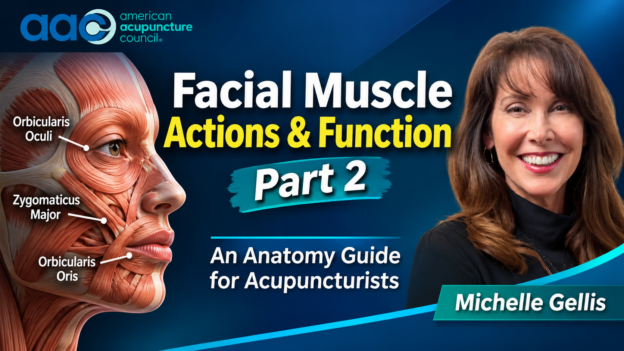
Facial Muscle Actions and Function: An Anatomy Guide for Acupuncturists
Understanding facial muscle actions helps acupuncturists connect visible expressions with the anatomy that produces them. In this American Acupuncture Council presentation, Michelle Gellis discusses facial muscle function in the context of facial acupuncture education. In addition, this companion article reviews the major muscle groups, their actions, and practical anatomical considerations for clinicians and students.
Transcript: The original AAC listing advertises a downloadable transcript. The exact downloadable asset URL could not be independently retrieved during this revision. Restore the original “Click here to download the transcript” link from the existing WordPress media/link field before publication; do not replace it with an unverified URL.
Why facial muscle actions matter in facial acupuncture
Facial muscles do more than create expressions. For example, they help close the eyelids and lips, move the nostrils, support oral function, and coordinate movements used in speaking and eating. Moreover, unlike many skeletal muscles, numerous muscles of facial expression insert into skin or superficial connective tissue. As a result, their contraction changes the position of the overlying skin.
Most muscles of facial expression receive motor innervation from the facial nerve (cranial nerve VII). By contrast, the muscles of mastication, including the masseter and temporalis, are primarily supplied by the mandibular division of the trigeminal nerve (cranial nerve V3). Therefore, this distinction matters when assessing facial movement: not every muscle around the face belongs to the facial-expression group.
Key facial muscles and their primary actions
Forehead and eyebrow
Frontal belly of the occipitofrontalis (frontalis): elevates the eyebrows and produces horizontal forehead lines.
Corrugator supercilii: draws the eyebrows medially and downward, contributing to vertical glabellar lines.
Procerus: pulls the medial brow downward and contributes to transverse lines over the bridge of the nose.
Periorbital region
Orbicularis oculi encircles the eye. More specifically, its palpebral portion supports gentle eyelid closure, including blinking, while its orbital portion contributes to forceful closure. For this reason, the muscle is essential to normal eyelid function and should be distinguished from muscles that elevate the upper eyelid, which have different innervation and function.
Nose and upper lip
Nasalis: its portions help compress or widen the nostrils.
Levator labii superioris alaeque nasi: elevates the upper lip and can assist nostril dilation.
Levator labii superioris: elevates the upper lip.
Zygomaticus minor: elevates the upper lip and contributes to the nasolabial expression pattern.
Cheek and mouth
Zygomaticus major: draws the corner of the mouth upward and laterally, contributing to smiling.
Levator anguli oris: elevates the corner of the mouth.
Risorius: draws the corner of the mouth laterally.
Buccinator: compresses the cheek against the teeth and helps keep food between the dental surfaces during chewing. It also contributes to blowing and sucking.
Orbicularis oris: closes and protrudes the lips; it is important for articulation and oral competence.
Lower lip, chin, and neck
Depressor anguli oris: draws the corner of the mouth downward.
Depressor labii inferioris: lowers and everts the lower lip.
Mentalis: elevates and protrudes the lower lip and wrinkles the skin of the chin.
Platysma: tenses superficial skin of the lower face and neck and can assist in depressing the lower lip and mandible.
Clinical interpretation: assess movement, not just appearance
Facial expressions usually arise from coordinated activity across several muscles rather than from one muscle acting alone. For example, a smile involves more than the zygomaticus major; the upper lip, eyelids, cheeks, and other perioral muscles contribute to the overall pattern. Consequently, functional assessment should compare movement at rest and during specific tasks, such as raising the eyebrows, closing the eyes gently and firmly, smiling, pursing the lips, showing the teeth, and puffing the cheeks.
For acupuncturists, anatomical knowledge can help organize observation, communication, and treatment planning. In practical terms, it can also help clinicians describe the region and tissue layer they intend to address. However, anatomy alone does not establish that needling a particular muscle will produce a specific cosmetic or functional result. Instead, treatment choices should reflect the patient’s presentation, practitioner training, scope of practice, and the limits of the available evidence.
Safety and professional considerations
Facial needling requires precise anatomical knowledge and appropriate training. Because the face contains variable superficial and deeper neurovascular structures, risk differs by location, depth, angle, and technique. Possible adverse events include pain, bleeding, bruising, and infection. Furthermore, deeper or poorly planned needling can create additional risk. For that reason, use clean-needle practices, obtain appropriate informed consent, apply conservative technique, and maintain a clear referral plan when findings fall outside your competence.
New or sudden facial weakness, asymmetry, difficulty closing an eye, speech changes, or other acute neurological symptoms require prompt medical assessment rather than an assumption that the problem is muscular or cosmetic. Likewise, persistent facial dysfunction warrants appropriate medical evaluation. Most importantly, acupuncture should never delay emergency assessment or indicated medical care.
Continue your facial acupuncture education
Explore these related American Acupuncture Council presentations:
Knowing the actions and innervation of facial muscles gives acupuncturists a clearer framework for observing facial movement and discussing treatment goals. Ultimately, the most useful clinical approach combines anatomical precision with functional assessment, sound needling judgment, and appropriate referral. To explore these concepts further, watch Michelle Gellis’s presentation and use the transcript when AAC restores the original download link.
American Acupuncture Council: AAC supports the professional acupuncture community with educational resources and practice-focused information. Visit American Acupuncture Council to explore additional resources.
Educational disclaimer: This article is for professional education and general information. It does not provide individualized medical advice, establish a diagnosis, or replace appropriate medical evaluation. Practitioners are responsible for working within their training, licensure, and applicable laws and standards.
References
Fakoya AO, Hohman MH, Westbrook KE, Varacallo M. Anatomy, Head and Neck: Facial Muscles. StatPearls [Internet]. Updated April 20, 2024. NCBI Bookshelf.
Cosmetic Acupuncture for Facial Aging: Anatomy, Mechanobiology, and Clinical Evidence—A Narrative Review. Journal of Cosmetic Dermatology. First published October 16, 2026. https://doi.org/10.1111/jocd.71245.
Does Acupuncture Malpractice Insurance Protect Your Entire Practice?
Acupuncture malpractice insurance coverage is essential for protecting your professional practice, but does your policy protect your entire acupuncture business? If you operate a clinic, employ other practitioners, work with independent contractors, or provide services at multiple locations, the answer may be more complicated than you think.
Professional liability insurance protects against certain claims arising from professional services. However, it does not automatically mean that every practitioner, business activity, location, or physical asset associated with your clinic has coverage.
As your acupuncture practice grows, your insurance needs may change. Understanding the difference between individual malpractice protection and broader business insurance can help you identify potential coverage gaps before a claim occurs.
What Does Acupuncture Malpractice Insurance Coverage Include?
Acupuncture malpractice insurance, also known as professional liability insurance, generally addresses allegations of negligence or other covered wrongful acts associated with professional services. These claims may involve treatment decisions, clinical procedures, patient injuries, or other professional activities, depending on the policy.
However, operating an acupuncture clinic involves risks beyond the treatment itself. Patients and visitors may experience accidents on the premises. Employees may have separate professional liability exposures. Business equipment can be damaged or stolen. A landlord or another organization may also request protection under your insurance arrangements.
These exposures do not necessarily fall under the same insurance coverage.
The National Association of Insurance Commissioners explains that medical professional liability insurance addresses covered liability claims and associated defense costs. It also distinguishes claims-made policies from occurrence-based policies, which respond differently depending on when an incident occurs and when a claim is reported.
For an acupuncture practice owner, the important question is not simply whether you have malpractice insurance. It is whether your actual acupuncture malpractice insurance coverage addresses the risks associated with the way your business operates.
Does Your Acupuncture Insurance Cover Employees and Independent Contractors?
One of the most important questions for an acupuncture clinic owner concerns the people working in the practice.
Consider a clinic with several licensed acupuncturists. Each practitioner provides treatments, maintains patient records, and makes independent clinical decisions. If a patient alleges negligence involving one practitioner, the clinic owner may also become involved in the resulting claim.
Do not assume that the owner’s individual malpractice policy automatically covers every practitioner working in the clinic.
Employees and independent contractors may have different insurance arrangements. Their professional liability coverage should be verified individually, and the clinic owner should determine whether the business itself has appropriate protection for its potential liability.
Ask your insurance representative:
Are employees covered under the clinic’s professional liability policy?
Must each licensed practitioner maintain an individual malpractice policy?
Are independent contractors included, or must they obtain their own coverage?
Does the policy address claims against the business arising from another practitioner’s professional services?
Are there specific requirements for documenting each practitioner’s coverage?
Written confirmation matters. A verbal assurance or a general description of a policy is not a substitute for reviewing its actual terms and endorsements.
How Do Additional Practice Locations Affect Insurance Coverage?
Expanding your acupuncture practice can introduce additional insurance considerations.
You might begin with one treatment room and eventually operate a larger clinic, establish another office, or provide acupuncture services at a wellness center or other facility.
Each location should be evaluated against the policy’s definitions of covered premises, professional services, and insured activities.
Questions to consider include:
Does the policy identify or include all locations where you provide treatment?
Are temporary or shared treatment facilities addressed?
Does coverage extend to services provided away from your primary office?
Does a landlord or facility require additional-insured status?
Are there special requirements for off-site services or travel?
Do not assume that opening another office automatically updates your insurance. Notify your insurance representative when your practice changes and obtain confirmation of any necessary policy changes.
Does Acupuncture Malpractice Insurance Cover Additional Treatment Modalities?
Acupuncture practices often evolve beyond the services initially offered when the practitioner purchased coverage.
A practitioner may add herbal medicine, cupping, moxibustion, gua sha, facial acupuncture, injection therapy, or other services as professional training and business needs develop.
However, coverage for one professional service does not automatically establish coverage for every additional modality.
Before introducing a new service, review the policy’s covered professional services, exclusions, endorsements, and any underwriting requirements.
The American Acupuncture Council explains that its professional liability program generally addresses services within the practitioner’s state-defined scope of practice, subject to specific policy exclusions. Its FAQ also identifies certain services, including injection therapy, that may require a separate application and underwriting approval.
Three questions deserve particular attention:
Is the service covered under the policy’s definition of professional services?
Is the service permitted within the practitioner’s applicable state scope of practice?
Does the insurer require additional documentation, training verification, or a special endorsement?
Insurance coverage and legal scope of practice are separate issues. Having insurance does not authorize a practitioner to provide services outside the law or professional licensing requirements.
Professional Liability vs. Premises and General Liability Insurance
Another common misunderstanding involves the difference between professional liability insurance and coverage for accidents occurring at the clinic.
Consider two situations.
Situation one: A treatment-related allegation. A patient claims that an acupuncture procedure caused an injury. This type of allegation may fall under professional liability coverage, subject to the policy terms.
Situation two: An accident in the waiting room. A patient slips on a wet floor while entering the clinic. This is generally a premises or general liability exposure rather than an allegation involving professional negligence.
The two situations involve different risks and may require different insurance coverage.
AAC describes premises liability coverage as protection addressing certain injuries or property damage involving invited guests at the clinic. Its general liability information also discusses broader exposures, including common areas, personal injury allegations, and certain property damage risks.
Practice owners should determine which coverage applies to their particular premises and operations instead of assuming malpractice insurance handles every accident.
Does Your Acupuncture Practice Insurance Cover Equipment and Business Property?
Your acupuncture practice depends on physical assets that may represent a substantial investment.
Treatment tables, office furniture, computers, specialized equipment, and other business property can be lost, stolen, or damaged.
Professional liability insurance is not automatically property insurance. A policy designed to address allegations of professional negligence should not be assumed to cover the replacement cost of business equipment.
The American Acupuncture Council describes a Business Personal Property option that can cover qualifying business property, including treatment tables and furniture, subject to the policy’s limits, deductible, and conditions.
When evaluating this protection, ask:
Which business assets qualify for coverage?
What are the policy limits and deductible?
Are computers and specialized treatment equipment included?
Does coverage apply at every business location?
Are theft, fire, water damage, and other potential losses treated differently?
Make sure the amount of property coverage reflects the value of the assets you actually need to protect.
Additional Insured Coverage: Who Needs It?
Landlords, wellness centers, healthcare facilities, and other organizations sometimes request additional-insured status as part of their contractual arrangements with practitioners.
An additional insured is an entity or person added to an insurance policy through an endorsement. Depending on the policy wording, this arrangement may provide protection for certain claims arising from the named insured’s activities.
AAC explains that its additional-insured option may provide defense and indemnity protection to an eligible additional insured when a claim results from the named insured’s actions or inactions, subject to the applicable policy provisions.
AAC also describes shared-limit and separate-limit options. With shared limits, the named insured and additional insured use the same liability limits. Separate limits provide distinct limits for each, subject to the endorsement.
It is important to understand that additional-insured status does not automatically make the additional insured a covered practitioner for their own independent professional negligence. The actual endorsement determines the extent of protection.
If your landlord or business partner requests additional-insured status, ask the insurance provider to review the contractual requirement and confirm the appropriate endorsement in writing.
When Should You Review Your Acupuncture Malpractice Insurance Coverage?
Your insurance should reflect your current practice, not simply the way your business operated when you first purchased coverage.
Review your arrangements whenever you:
Hire an employee or engage an independent contractor.
Open another treatment location.
Move your existing clinic.
Introduce a new treatment modality.
Begin providing services at another facility.
Change your business ownership or legal structure.
Enter a new lease or facility agreement.
Purchase expensive equipment or other business property.
Also review your policy at renewal. Pay attention to changes in coverage limits, exclusions, endorsements, premiums, and reporting requirements.
For claims-made policies, understand the retroactive date and any applicable extended reporting period provisions. An occurrence policy generally responds to covered incidents that occur during the policy period, even when the claim is made later. These distinctions can become particularly important when changing insurance providers or retiring.
Acupuncture Insurance Coverage Review Checklist
Use these questions when reviewing your current insurance arrangements:
Does my professional liability policy cover all the services I currently provide?
Are all licensed practitioners in my clinic appropriately insured?
Have I confirmed the insurance arrangements for independent contractors?
Does my policy address my current business entity and ownership structure?
Are all practice locations properly identified or included?
Do I have appropriate premises and general liability protection?
Is my business equipment adequately insured?
Do landlords or other organizations require additional-insured endorsements?
Do I understand my liability limits, exclusions, deductibles, and reporting requirements?
Have I discussed recent changes in my practice with my insurance representative?
If you cannot confidently answer these questions, it may be time for a more thorough insurance review.
Protect Your Acupuncture Practice as It Grows
Running an acupuncture practice involves more than providing excellent patient care. It also requires attention to professional responsibilities, business operations, employees, facilities, and financial risks.
Acupuncture malpractice insurance coverage is an important part of that protection, but the right insurance arrangements depend on the complete picture of your practice.
The American Acupuncture Council has developed insurance programs specifically for acupuncture and related healthcare professionals. Its coverage options include professional liability and additional coverage choices that may address certain premises, property, and additional-insured exposures.
Rather than waiting until a claim or unexpected loss exposes a potential gap, take time to review your coverage today.
Not yet an American Acupuncture Council member? Request a quick quote and discuss your practice’s insurance needs with AAC.
Insurance coverage is governed by the applicable policy, endorsements, exclusions, conditions, and underwriting requirements. This article provides general educational information and is not legal, insurance, or professional advice. Consult your insurance representative regarding your specific coverage and applicable state requirements.
Patients and practitioners often misunderstand Medicare acupuncture coverage. A patient may see an advertisement saying that Medicare covers acupuncture, assume every Medicare plan includes the same benefit, and arrive at your practice expecting direct coverage. For acupuncturists, the distinction between Original Medicare and Medicare Advantage is essential. In this presentation, Sam Collins of the American Acupuncture Council explains how to approach those conversations, verify benefits, and avoid promising reimbursement before anyone verifies the details.
Read along:Download the original presentation transcript. AAC notes that its transcripts may contain spelling or grammatical errors; AAC recommends that readers watch the presentation while they read.
“Medicare” is not a single, uniform acupuncture benefit. Patients may have Original Medicare (Parts A and B), a Medicare Advantage plan (Part C), or other coverage arrangements. A television advertisement or a neighbor’s experience does not establish what a particular member’s plan covers. The practice must identify the exact plan and verify its terms before scheduling or billing as though the plan covers treatment.
What Original Medicare Part B covers
Medicare Part B covers acupuncture, including dry needling, only for qualifying chronic low back pain under National Coverage Determination (NCD) 30.3.3. CMS defines qualifying chronic low back pain as nonspecific pain that lasts at least 12 weeks, has no identifiable systemic cause, and does not relate to surgery or pregnancy.
The benefit permits up to 12 visits in 90 days. Medicare may cover eight additional sessions when the patient demonstrates improvement, up to 20 treatments in a 12-month period. Stop treatment if the patient does not improve or begins to regress. This NCD excludes acupuncture for conditions other than qualifying chronic low back pain.
There is also a provider and billing distinction. Medicare.gov explains that Medicare does not pay licensed acupuncturists directly for their services. Under the NCD, physicians may provide acupuncture when they meet state requirements. The NCD requires physician assistants, nurse practitioners/clinical nurse specialists, and auxiliary personnel to meet specified graduate-level acupuncture education and state-licensure criteria. Medicare rules also require auxiliary personnel to work under the applicable level of supervision. This is not the same as an ordinary referral to an independent acupuncturist.
How Medicare Advantage (Part C) is different
Medicare Advantage plans must cover the Medicare Part A and Part B benefits their members are entitled to receive. Some plans may also offer additional supplemental benefits that go beyond Original Medicare. A plan may offer a routine-acupuncture benefit, but plans do not all offer this benefit. Never assume coverage based only on the insurer’s name or a general advertisement.
Supplemental benefits can have their own definitions, visit limits, eligible services, provider qualifications, network rules, cost-sharing, referral requirements, and prior-authorization conditions. These details can vary by plan, service area, and contract year. A benefit that one UnitedHealthcare, Aetna, Cigna, or other plan document lists does not prove that another plan from the same company covers the service.
Sam’s presentation uses a routine-acupuncture benefit as an example of how some Medicare Advantage plans may provide broader access than Original Medicare. Use that example as a reason to investigate. It does not guarantee coverage, unlimited visits, or reimbursement for every service in an acupuncture practice.
A practical Medicare verification checklist for acupuncturists
Before telling a patient that the plan covers acupuncture, verify the following directly with the plan or through a reliable eligibility and benefits process:
Exact plan identity: Record the full plan name, plan type, member ID, and effective dates. Do not rely on the carrier name alone.
Benefit category: Determine whether the inquiry concerns Original Medicare coverage for qualifying chronic low back pain or a separate Medicare Advantage supplemental acupuncture benefit.
Covered indications and services: Confirm which diagnoses, acupuncture services, evaluation services, and related modalities the plan covers. Do not assume every service within your scope is covered.
Provider eligibility and network: Confirm whether the plan’s credentialing, licensure, and network rules include the individual acupuncturist and practice location.
Utilization rules: Ask about visit limits, frequency limits, referrals, prior authorization, medical-necessity criteria, and any requirement to demonstrate progress.
Patient financial responsibility: Confirm copayments, coinsurance, deductibles, non-covered services, and whether the patient could owe the full charge.
Billing instructions: Verify the applicable codes, modifiers, payer ID, claim submission route, documentation requirements, and timely-filing rules using current plan guidance.
Effective year: Recheck benefits for the correct contract year. A benefit or provider network can change, even when the insurance company’s name remains the same.
Keep a dated record of the verification, including the representative or portal used, reference number when available, the specific questions asked, and the answers received. Eligibility and benefit verification does not guarantee claim payment. The plan still applies its terms, medical-necessity review, coding, documentation, and other applicable requirements when it processes the claim.
Help patients understand their options without guaranteeing coverage
Use plain language. Explain that Original Medicare’s national acupuncture benefit is narrow and that some Medicare Advantage plans may offer additional benefits. If a patient’s plan does not cover the proposed service, discuss the expected self-pay cost and available payment arrangements before treatment. Give the patient a written estimate when appropriate and document the financial discussion and consent.
During Medicare Open Enrollment, October 15 through December 7, beneficiaries can compare or change coverage for the following year. Acupuncturists can encourage patients to review official plan documents and Medicare’s Plan Finder, but should avoid steering patients toward a particular plan or making unsupported claims about which plan is best. Patients should weigh their full health and financial needs when they choose coverage.
Keep your Medicare and insurance knowledge current
Do not treat Original Medicare rules and Medicare Advantage benefits as interchangeable. The safest practice is to understand the national Original Medicare policy, then verify the actual supplemental benefit and billing rules for each Medicare Advantage plan. Review plan-year updates, train front-office and billing personnel, and revisit verification procedures whenever contracts or benefits change.
Medicare Part B covers acupuncture, including dry needling, only for qualifying chronic low back pain under NCD 30.3.3. This policy excludes other acupuncture indications from national coverage.
Can a licensed acupuncturist bill Original Medicare directly?
Medicare.gov explains that Medicare does not pay licensed acupuncturists directly for their services. The NCD allows specified practitioners and qualifying auxiliary personnel to provide covered acupuncture when they meet all applicable requirements.
Do Medicare Advantage plans cover routine acupuncture?
Some Medicare Advantage plans may offer supplemental routine-acupuncture benefits, but plans vary in availability and conditions. Verify the member’s exact plan, year, provider status, covered services, limits, and authorization requirements.
Does a benefits verification guarantee payment?
No. Verification is an important step, but the plan still evaluates its contract, claim requirements, medical necessity, documentation, coding, and final adjudication before it pays.
Learn more from the American Acupuncture Council
The American Acupuncture Council supports acupuncture professionals with practice resources, education, and professional liability coverage. Explore the AAC Network for additional practice and billing education. For information about professional liability protection, visit AAC Acupuncture Professional Liability Insurance. You can also visit the American Acupuncture Council website to learn more.
Educational disclaimer: This article is for general educational and informational purposes only. It is not legal, billing, coding, reimbursement, or medical advice and does not guarantee coverage or payment. Medicare and Medicare Advantage requirements can change and may vary by plan, contract year, location, and individual circumstances. Verify current requirements with CMS, the applicable Medicare Administrative Contractor, and the patient’s health plan. Consult qualified billing, compliance, or legal professionals when appropriate.
Choosing malpractice insurance is not simply a matter of comparing premiums and coverage limits. Acupuncturists also need to understand how their policy responds when a patient makes a claim—particularly when that claim arrives months or even years after treatment.Two common professional liability insurance structures are occurrence-based and claims-made coverage. Both can protect practitioners against eligible professional liability claims, but they operate differently.Understanding the distinction can help you make more informed decisions when purchasing insurance, changing carriers, expanding your practice, or planning retirement.
Watch: The Two Malpractice Policy Structures Every Acupuncturist Needs to Understand
1. What Is an Occurrence Malpractice Insurance Policy?
An occurrence policy generally provides coverage for eligible incidents that occur during the policy period, regardless of when the claim is subsequently made. The important consideration is the date of the incident, rather than the date the patient files a claim.
Example of occurrence coverage
Suppose an acupuncturist has an occurrence policy from January through December 2026. A patient receives treatment in June 2026. Two years later, in June 2028, the patient alleges that the treatment caused an injury and files a malpractice claim.
If the alleged incident falls within the policy’s coverage and satisfies its other requirements, the 2026 policy may respond even though the policy is no longer active.
This is an important characteristic of occurrence coverage: ending or changing the policy does not ordinarily eliminate coverage for eligible incidents that occurred during its effective period.
Practical consideration: Practitioners generally do not need to purchase separate tail coverage simply because an occurrence policy expires or they change insurers. Other policy conditions, exclusions, limits, and reporting requirements still apply.
2. What Is a Claims-Made Malpractice Insurance Policy?
A claims-made policy generally responds when a claim is first made during the applicable policy period and satisfies the policy’s reporting requirements. The alleged incident must also fall on or after the policy’s retroactive date.
Two important dates therefore matter:
When the alleged professional incident occurred.
When the claim was first made and reported, as required by the policy.
Example of claims-made coverage
Imagine an acupuncturist has a claims-made policy that begins January 1, 2026, with a retroactive date of January 1, 2026. A patient receives treatment in June 2026 and makes a claim in June 2027.
If the practitioner has maintained eligible continuous coverage and the claim meets the policy’s reporting requirements, the insurer may respond.
Now suppose the practitioner cancels the policy at the end of 2026 and does not arrange appropriate extended reporting coverage or replacement prior-acts coverage. When the patient makes a claim in 2027, the former policy may no longer respond because the claim was made after the applicable reporting period ended.
Practical consideration: Claims-made coverage may have lower initial premiums, depending on the insurance program. Practitioners should understand how premiums may develop over time and what happens when coverage ends.
3. What Is a Retroactive Date?
The retroactive date establishes how far back a claims-made policy can cover eligible professional services or incidents. Generally, an incident occurring before the retroactive date will not qualify for coverage under that claims-made policy, even if the claim is made during the current policy period.
For example:
Policy effective date: January 1, 2026.
Retroactive date: January 1, 2024.
Alleged incident: June 2024.
Claim reported: March 2026.
The incident occurred after the retroactive date, and the claim was made during the policy period. Subject to all other policy requirements, coverage may apply. An incident from December 2023, by contrast, occurred before the retroactive date and generally would not qualify.
Important: When renewing or changing carriers, verify that your retroactive date is preserved when appropriate. Do not assume a new policy automatically includes your previous coverage history.
4. What Is Tail Coverage?
Tail coverage, formally known as an extended reporting period (ERP), allows eligible claims arising from incidents during the applicable claims-made coverage period to be reported after the policy terminates.
It can be particularly important when a practitioner retires, changes insurance carriers, closes a clinic, stops practicing, or cannot continue renewing an existing claims-made policy.
Tail coverage generally extends the time available to report eligible claims. It does not ordinarily extend the period during which new professional incidents can occur.
Why tail coverage matters
Suppose you treated a patient in 2025 while maintaining a claims-made policy. You subsequently retire and terminate the policy in 2026. If the patient makes a claim in 2028, the original policy may not respond unless an applicable extended reporting provision or other coverage arrangement is in place.
An ERP may preserve the ability to report eligible claims arising from the earlier covered period. Before terminating a policy, ask whether tail coverage is available, whether it is included in any circumstances, whether it costs extra, whether the extension is limited or unlimited, and what purchase deadlines apply. Never assume an automatic extension or retirement provision exists.
5. What Happens When You Switch Insurance Companies?
Changing insurance carriers deserves particular attention when you have claims-made coverage. The goal is to avoid a gap between the coverage protecting your previous professional services and the policy that will protect you going forward.
Prior-acts coverage (sometimes called nose coverage): A new insurer may agree to cover eligible incidents that occurred before the new policy began, subject to an accepted retroactive date and underwriting conditions.
Tail coverage: Your previous insurer may provide an extended reporting period so you can report eligible claims after the former policy terminates.
These arrangements can help maintain continuity, but they are not interchangeable in every circumstance. Before switching, coordinate the effective dates, retroactive date, reporting obligations, and written confirmation of coverage with both insurers.
6. Which Malpractice Insurance Structure Is Better for Acupuncturists?
There is no universally correct answer. The appropriate policy depends on the practitioner’s circumstances, financial considerations, career stage, and the actual terms of the insurance contract.
Consideration
Occurrence
Claims-made
Primary coverage trigger
Date of covered incident
Date claim is made and reported
Retroactive date
Generally not applicable
Usually applicable
After policy termination
Generally continues for covered incidents during the policy period
Requires applicable continuation or extended reporting arrangements
Tail coverage
Generally unnecessary
May be necessary
Initial premium
May be higher
May be lower
Long-term planning
Simpler reporting structure
Requires attention to continuity and termination
The table describes general policy characteristics, not a guarantee of coverage under any particular contract.
For new graduates, an initially lower claims-made premium may be attractive. However, it is important to understand future premium development and potential termination costs. Established practitioners should consider their accumulated coverage history and the consequences of changing carriers. Practitioners approaching retirement should evaluate whether their claims-made policy includes retirement provisions or whether purchasing an ERP will be necessary.
7. Questions Every Acupuncturist Should Ask Before Purchasing Coverage
Is the policy occurrence-based or claims-made?
If claims-made, what is the retroactive date?
What reporting deadlines apply when a claim or incident occurs?
Is extended reporting coverage available, and what does it cost?
Can prior-acts coverage be maintained if I change carriers?
Does the policy cover the specific services and modalities I provide?
Are my practice locations and professional entities properly identified?
What are the per-claim and aggregate coverage limits?
What exclusions, deductibles, and other conditions apply?
What happens to my coverage if I retire, close my practice, or stop practicing?
Do not rely exclusively on a sales summary. Request and review the actual policy, endorsements, and applicable coverage documents.
8. Why Malpractice Insurance Should Be Part of Your Risk Management Strategy
Insurance is an important part of responsible practice management, but it does not replace good clinical procedures. Acupuncturists should maintain appropriate patient screening, informed consent, safe needling practices, accurate clinical documentation, infection-control procedures, and appropriate referrals.
When an adverse event or patient complaint occurs, follow the policy’s notification requirements promptly. Preserve relevant records and avoid making statements or taking actions that could compromise the handling of a potential claim.
A well-selected insurance policy and sound clinical risk-management procedures work together to support a more resilient practice.
Conclusion: Understand Your Policy Before You Need It
Occurrence and claims-made malpractice insurance can both provide valuable professional liability protection. Their most important difference is how coverage is triggered and what happens when the policy ends.
Occurrence coverage generally follows the covered incident. Claims-made coverage generally depends on when the claim is made and reported, together with the applicable retroactive date and reporting provisions.
Before purchasing, renewing, switching carriers, or retiring, understand exactly how your policy works.
Explore Malpractice Insurance with the American Acupuncture Council
The American Acupuncture Council provides malpractice insurance resources for acupuncture professionals. Review your options and ask questions about the policy structure, coverage terms, and requirements that apply to your practice.
Protect your practice with informed insurance decisions.
Editorial note: Confirm and insert the exact source documents and links reviewed by the editor before publication. Do not treat general educational references as a substitute for the policy contract.
Educational Disclaimer: This article provides general educational information about professional liability insurance. It is not legal advice, insurance advice, or a substitute for reviewing your actual policy. Coverage definitions, exclusions, reporting requirements, retroactive dates, and extended reporting provisions vary by insurer and contract. Consult your insurance representative, qualified insurance professional, or legal counsel regarding your particular circumstances.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept”, you consent to the use of ALL the cookies.
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Any cookies that may not be particularly necessary for the website to function and is used specifically to collect user personal data via analytics, ads, other embedded contents are termed as non-necessary cookies. It is mandatory to procure user consent prior to running these cookies on your website.