


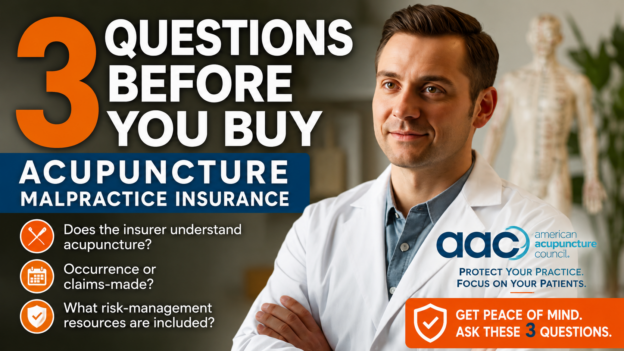
3 Questions to Ask Before Buying Acupuncture Malpractice Insurance
Choosing malpractice coverage is about more than finding a low premium. Before buying acupuncture malpractice insurance, ask three practical questions: Does the insurer understand acupuncture, how does the policy respond to claims over time, and what risk-management resources are included? These answers can affect how well the policy fits your practice.
Introduction
Choosing professional liability insurance is a practice-management decision, not simply a price comparison. For acupuncturists, the policy should fit the services you provide, the way your practice is structured, and your plans for changing carriers or eventually retiring. The American Acupuncture Council’s original post highlights three useful questions to ask before purchasing coverage: whether the program has acupuncture-specific experience, whether the policy is occurrence or claims-made, and what risk-management options are available.
Why acupuncture-specific insurance experience matters
A general healthcare policy is not automatically equivalent to coverage designed around acupuncture. Before buying a policy, ask the insurer to explain how it treats the services and modalities you actually provide and whether there are exclusions or underwriting requirements that could affect them.
AAC states that its professional liability program is designed for acupuncture and that coverage can vary according to the practitioner’s scope of practice and the services involved. Its current policy information also describes additional coverage options and a range of liability limits. Those details are reasons to read the actual policy and endorsements rather than relying on a summary or sales quote alone.
Question 1: Does the insurer have experience with acupuncture?
Ask whether the insurer and claims team routinely handle acupuncture professional liability matters. Then ask a more useful follow-up: “What exactly is covered for the services I perform?”
That question is especially important if your practice includes services beyond straightforward needling, such as herbal medicine, cupping, moxibustion, cosmetic or facial acupuncture, injection therapy, or another modality. Coverage depends on the policy language, underwriting, applicable exclusions, and the law and scope of practice where you work.
Question 2: Is the policy occurrence or claims-made?
This is one of the most important technical questions because the policy form determines when coverage can respond. The National Association of Insurance Commissioners explains that claims-made coverage generally responds when a claim is reported while the policy is in force, subject to the policy’s terms and any extended reporting period. Occurrence coverage generally responds based on when the covered event occurred, even if the claim is made after the policy has ended.
With a claims-made policy, ask what happens if you change carriers, stop practicing, or retire. You may need an extended reporting period, commonly called tail coverage, or prior-acts coverage from a new carrier. The exact solution depends on the policy and transition.
AAC’s current FAQ states that its claims-made option converts to occurrence coverage without charge after ten years and that retroactive coverage may be available for practitioners moving from another claims-made policy, subject to underwriting. Because insurance terms can change, practitioners should confirm the current policy wording and transition provisions before relying on those features.
Question 3: What risk-management options are included?
Insurance is only one part of risk management. Ask what resources the insurer provides to help reduce disputes and respond when a complaint develops.
AAC currently offers Preferred and Elite program options. Its FAQ states that the Elite program provides a premium discount when practitioners use approved arbitration and informed-consent forms as part of their intake process. AAC also describes claims and risk-management support for members.
Informed consent should not be treated as a substitute for sound clinical judgment, appropriate documentation, communication, referral, or compliance with state requirements. Likewise, an arbitration agreement may have legal and jurisdiction-specific requirements. Practitioners should use only forms approved for their program and practice and should obtain independent legal advice when appropriate.
What to compare before you buy
Before selecting a policy, compare more than the annual premium. At minimum, review the policy form; per-claim and aggregate limits; covered services and exclusions; defense provisions; prior-acts or retroactive coverage; tail or extended reporting provisions; additional insured and business-entity coverage where applicable; and risk-management resources.
Also ask how a claim or incident should be reported. A policy may impose notice requirements, and failing to follow them can create coverage issues. Keep the policy, endorsements, declarations, and approved forms together with your practice’s insurance records so that your staff can locate them quickly if a problem arises.
Benefits, limitations, and safety considerations
The main benefit of asking these questions is clarity. A policy that looks inexpensive may have a different policy form, exclusions, limits, or transition requirements than another policy. On the other hand, a higher premium does not automatically mean better coverage. The right comparison is between the actual protections and obligations in each policy.
Professional liability insurance also does not replace clinical risk management. Accurate patient histories, examination findings, treatment plans, informed consent, appropriate referrals, and detailed records remain important parts of safe practice. AAC’s guidance on patient records emphasizes documenting the reason for the visit, medications and allergies, clinical findings, diagnosis, treatment plan, and care provided.
Insurance requirements, scope-of-practice rules, arbitration law, and documentation requirements vary by jurisdiction. Practitioners should verify current requirements with the applicable licensing board, insurer, attorney, or other qualified professional.
A practical three-question checklist
Before you buy or renew, ask:
1. Does this insurer have meaningful experience with acupuncture and my specific services?
2. Is the policy occurrence or claims-made, and what happens to coverage for my past work if I change carriers, stop practicing, or retire?
3. What risk-management resources, forms, claims support, and program options are included—and what conditions apply?
Conclusion
The goal is not simply to buy malpractice insurance. It is to understand what you are buying before you need it. For acupuncturists, three questions provide a practical starting point: acupuncture-specific experience, policy form and long-term coverage, and risk-management support.
If you are comparing coverage, review the actual policy documents and ask the insurer to explain anything you do not understand. AAC provides acupuncture-focused professional liability information, coverage options, claims and risk-management resources, and a Quick Quote for practitioners who want to compare their options.
Educational disclaimer
This article is for educational purposes only and does not provide legal, insurance, financial, or clinical advice. Insurance coverage is governed by the actual policy, endorsements, exclusions, and applicable law. State licensing and insurance requirements vary. Consult your insurance professional, attorney, licensing board, or other qualified adviser regarding your specific circumstances.
Related American Acupuncture Council Resources
- AAC Acupuncture Professional Liability Policy
- AAC Professional Liability FAQ
- AAC Coverage Options
- AAC Claims Service & Risk Management
- Importance of Keeping Detailed Patient Records
- The Importance of Patient-Informed Consent
References
- American Acupuncture Council — original article
- AAC — Frequently Asked Questions
- AAC — AAC Policy
- AAC — Coverage Options
- AAC — Claims Service & Risk Management
- AAC — Importance of Keeping Detailed Patient Records
- AAC — The Importance of Patient-Informed Consent
- AAC — Acupuncture Malpractice Quick Quote
- National Association of Insurance Commissioners — Medical Malpractice Insurance
- AMA Insurance — Claims-Made vs. Occurrence Medical Malpractice Insurance
- TMLT — Claims-Made vs. Occurrence
Talk With AAC About Your Coverage Options
If you are comparing acupuncture malpractice insurance, AAC can help you review available coverage options and request a Quick Quote. Visit AAC’s Acupuncture Malpractice Quick Quote to begin.
This article is for educational purposes only and does not provide legal, insurance, financial, or clinical advice. Insurance coverage is governed by the actual policy, endorsements, exclusions, and applicable law. State requirements vary.
 There are a number of reasons why acupuncturists need liability insurance. For one thing, it provides peace of mind knowing that things will be taken care of in case someone files a legal malpractice complaint. For another, it takes care of the financing needed to cover the expenses in case a clinic staff figures in an accident and gets injured in the line of duty. An acupuncturist professional liability insurance can be designed so that it covers the compensation of that staff while he is away recovering.